
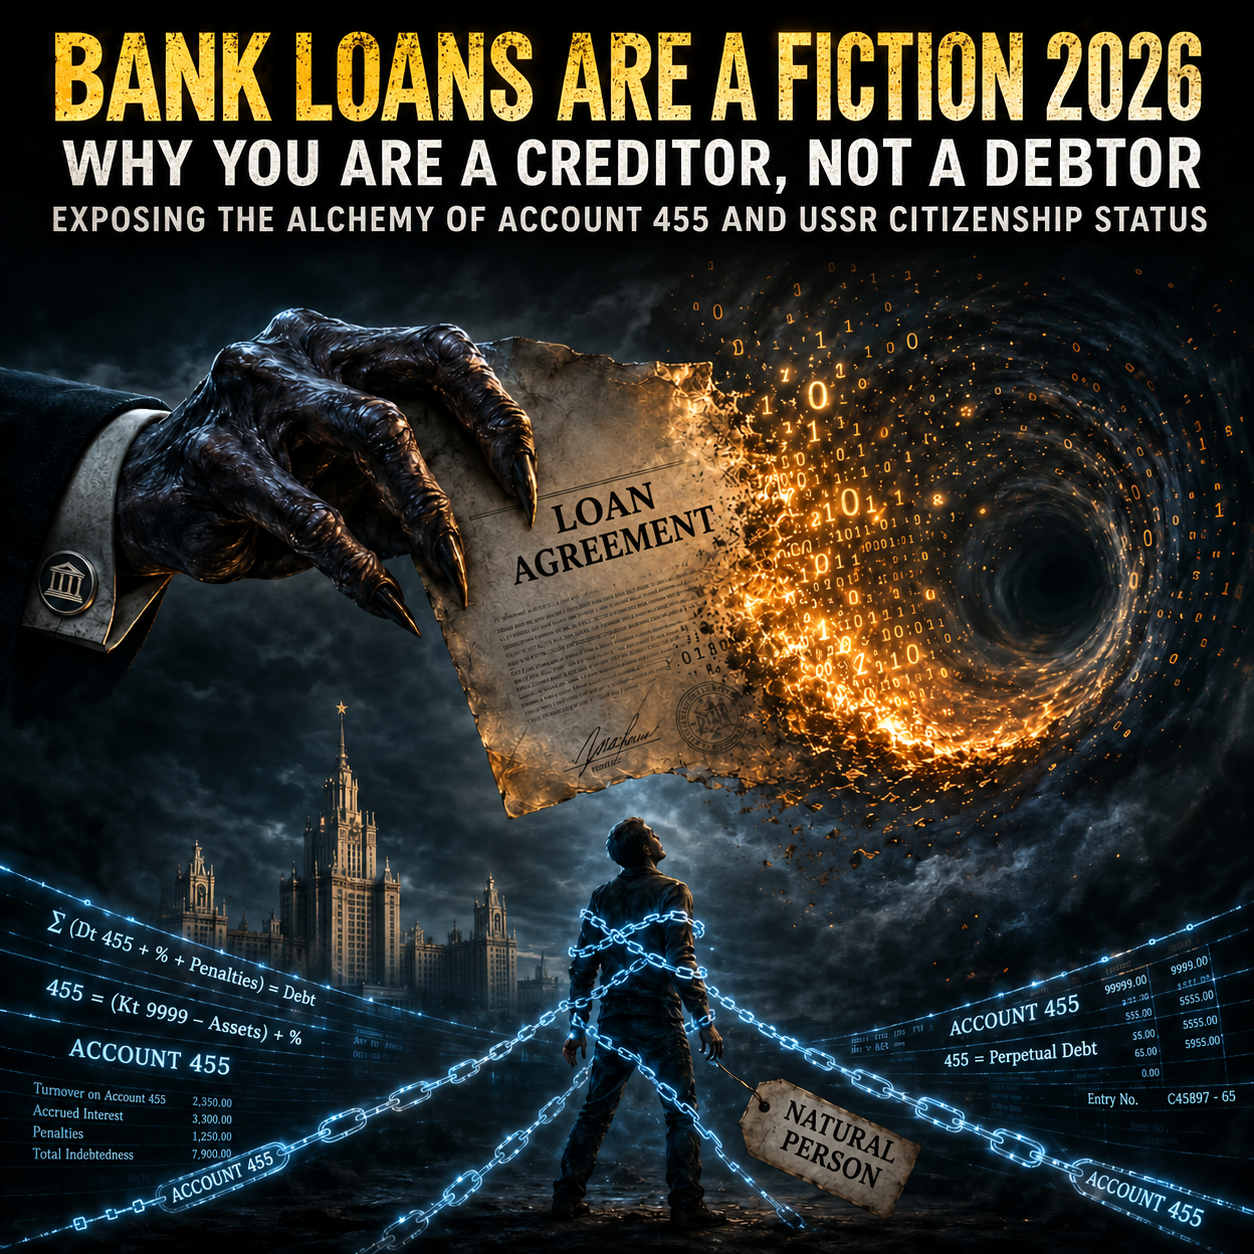
The bank “loan” that millions of citizens consider their debt is, in fact, a legal fiction. Commercial banks do not lend their own money. They create “money” from the borrower’s signature through accounting entries, turning the borrower into a “natural person” with no rights. We examine how this alchemy works and why a citizen of the USSR is entitled to have such an agreement declared void. Join Russia’s largest Telegram community: https://t.me/tassussr
The Legal Nature of the Russian Federation: A Joint-Stock Company or a Trading Company
The Russian Federation is not a sovereign state. It is a trading company that has already closed down and a corporate trust, registered in the state of Delaware (USA) and operating on the continental shelf of the USSR. All parts of this corporation, including the Central Bank and commercial banks (such as Sberbank PJSC), are private commercial companies. They have no lawful right to collect taxes, issue loans or, most importantly, deprive citizens of their sovereign status.
To explain: the concept of a “natural person” did not exist in the USSR. A citizen was an owner, a subject of law. In the Russian Federation’s corporate system, every person has been fraudulently assigned the status of a “natural person” — a legally dead debtor lacking legal capacity, in other words, a slave under Roman law.
Account 455: The Bank’s Debt, Not Its Asset
The key vulnerability of the banking system lies in its accounting records. The bank claims to have transferred money to the borrower. But from where, and to where?
Under Bank of Russia Regulation No. 385-П, account 455 is a loan account used to record loans issued. However, there is a crucial detail that banks conceal: this account reflects the bank’s obligation to the creditor — the person who actually provided the money.
When a bank transfers funds from account 455 to a natural person’s current account (account 408), it does so against its own debt obligation, rather than from its own assets. The bank has not lent its own money. It has lent someone else’s, without disclosing this fact to the borrower.
To explain: a neighbour owes you 1000 roubles. He comes over and says: “I’ll transfer 1000 roubles to you out of the debt I owe Petya.” He is not handing over his own money. He is simply reassigning a debt. That is exactly how a bank “loan” works.
The Bank Is an Intermediary, Not a Creditor
If the funds in account 455 do not belong to the bank but consist of other people’s deposits or an interbank loan, the bank acts as an intermediary rather than a creditor. It may not hold a licence for this activity. Moreover, the bank conceals the actual creditor from the borrower, directly violating Articles 10 and 12 of the Law “On Consumer Protection”. These articles require full and accurate information about the service to be provided. The identity of the person who supplied the money is an essential term of the agreement. Without this information, the transaction can be declared void.To explain: a deposit involves a depositor handing money to a bank for temporary safekeeping in return for a promise to repay it with interest. Harmless at first glance. But in terms of the logic of lending, a deposit is the same scam in reverse.
When you open a deposit account, you become a creditor, and the bank becomes your debtor. The bank receives actual cash. In exchange, it promises to repay the amount with a small addition (5–10% per annum). The bank does not keep your money in a safe. It immediately puts it to work: issuing “loans”, buying bonds and making interbank loans. Your funds pass out of your possession. All you receive is a digital entry in your online account. The money is no longer physically in the bank.
An analogy: you leave your coat in a cloakroom. You are given a ticket. You are certain that your coat is hanging where it should be. But the cloakroom attendant has secretly given it to someone else to take for a spin. Will the attendant give you your coat back when the “passenger” returns it?
In essence, a deposit is a transaction in which you are the creditor, but the bank dictates the terms, not you. You hand over something of real value. The bank creates a liability for itself (your deposit is its debt to you) and, at the same time, an asset (it invests your money and earns income). The deposit agreement does not specify exactly where the bank puts the funds. You trust it as a “safe repository”, while in reality you are financing its lending scam. The bank earns many times more from your money than it pays you. You pay for its usury business out of your own pocket and at your own risk.
If the bank collapses (and this will happen to many in 2026–2027), you will lose your actual savings. The bank will keep its profits. Deposits are insured only within a system that is itself a pyramid scheme.
If you already have a deposit account, demand a statement from the bank showing exactly where your funds have been placed. If the bank refuses, document the refusal. This will serve as your evidence at a future tribunal that you were misled. Close deposit accounts early, even if you lose the interest. It is better to lose the interest than the entire principal when the system collapses.
A Credit Agreement May Involve No Funds Being Advanced and Be Deemed Never to Have Been Concluded
Article 812 of the Civil Code of the Russian Federation delivers the final blow to the banking fiction. It states that a borrower is entitled to challenge a loan agreement on the grounds that no funds were advanced if the money was not actually received.
What do we see in the case of a bank “loan”? The statement for the borrower’s current account 408 shows that the funds came from account 455 at the same bank. No actual transfer of money from outside took place. The bank made an internal accounting entry — it recast its debt to a third party as the borrower’s debt. Consequently, no funds were advanced under the credit agreement, and it must be declared never to have been concluded under Article 812 of the Civil Code of the Russian Federation. The borrower did not borrow any money. They signed a promissory note that the bank used as an instrument to create money out of thin air.
The Alchemy of Lending: How the Bank Steals Your Asset
As far back as 2014, the Bank of England officially acknowledged that commercial banks do not lend their own money. Lending means creating money from the borrower’s signature. Your agreement is a promissory note. How does this accounting robbery work? A commercial bank takes your promissory note into account 91202 (as an asset), while conjuring up figures for you in account 455 (as a debt). This is the theft of your asset through the manipulation of accounting records, a practice known since the days of Luca Pacioli.
Moreover, under Federal Law No. 224-ФЗ and through subsidy mechanisms (Government Resolutions No. 1121, No. 566 and others), the state uses citizens’ taxes to pay the commercial bank additional subsidies for your loan. The bank profits both from you and from the public purse.
Banks have no licence to issue loans — only to provide monetary intermediation
A key fact that banks conceal: not a single commercial bank in the territory of the former Russian Federation holds a licence to issue loans. The banking licence issued by the Central Bank of the Russian Federation permits only monetary intermediation — accepting deposits and placing funds. It does not permit creating money out of thin air or lending as such.
Why? Because the Central Bank of the Russian Federation itself is a branch of the US Federal Reserve System (Fed), rather than a state body. The Central Bank of the Russian Federation is registered as a private corporation, and its shareholders are the same entities that own the Fed. Consequently, the Central Bank of the Russian Federation has no lawful right to issue lending licences. Its jurisdiction is corporate and American, rather than sovereign and Soviet.
Thus, when a bank “gives you a loan”, it acts without a licence, engaging in unlawful banking activity. All such agreements are void from the moment they are signed.
To explain: a person without a driving licence gets behind the wheel and carries passengers. A bank does the same thing when it “issues a loan” without the appropriate licence. Its actions are unlawful, and the agreement has no legal effect.
The Credit Agreement: A Deliberate Lie and Deception
When arranging a loan, banks give the citizen a standard agreement to sign, drafted to obscure the legal nature of the transaction. The agreement does not state that: the bank does not lend its own money; the money is created from the borrower’s signature; the bank acts only as an intermediary; the actual creditor is a third party (a depositor, another bank or the borrower themselves through a promissory note).
This is outright deception, violating Articles 10 and 12 of the Law “On Consumer Protection”. The citizen is not provided with full information about the service. They sign the agreement believing they are borrowing “the bank’s money”, although in reality the bank gives them nothing but figures in an account and a debt obligation.
You Are the Creditor, You Are Not the Borrower
Thus, the borrower did not borrow any money. They are a creditor who financed a commercial bank with their personal asset (their signature, their promissory note). They are the beneficial owner who has been unlawfully deprived of the right to dispose of their property.
Banks engage in usury — an activity prohibited in the territory of the USSR.
Usury means lending money at interest when the creditor does not risk their own capital but profits from someone else’s need. In the territory of the Soviet Union, usury was prohibited and criminally punishable. Decrees of the Soviet authorities abolished interest-bearing loans as an exploitative practice.
All modern commercial banks operating in the territory of the USSR under the guise of “credit institutions” are essentially engaged in precisely this usury. They produce nothing, risk none of their own funds (because they have none), and simply charge interest on interest, driving citizens into debt bondage.
Under Soviet legislation (the 1960 Criminal Code of the Russian Soviet Federative Socialist Republic (RSFSR), Art. 154), private usury was subject to prosecution. Although this article has formally been repealed, the moral and legal prohibition remains in international norms and in the wartime laws of the USSR.
TASS APPEAL TO THE CITIZENS OF THE SOVIET UNION:
The Telegraph Agency of the Soviet Union calls on every citizen of the USSR to be aware of their legal rights! You are not the bank’s debtor. You are a creditor whose personal asset has been stolen. Do not sign promissory notes or acknowledge debts created out of thin air. Demand that banks disclose the actual creditors. Remember: your signature is your asset. Do not hand it over to fraudsters! Restore your Sovereign status as a citizen of the USSR, and no banking alchemy will have power over you. Act!
All news concerning the People’s Referendum will be updated in a dedicated section: https://tass.news/category/ussr/vserossijskij-referendum/